There are no Perth suburbs where it is cheaper to buy a house than rent one, according to new research from REIWA.
The research compared the median monthly house rent price for a suburb with loan repayments on a mortgage based on its median house price. It also reviewed the unit market.
REIWA President Suzanne Brown said the data showed it was clearly cheaper to rent than buy and assuming tenants would or could buy when an investor sold was unrealistic.
"Five years ago, it was easier to make the transition from renting to home ownership, but due to strong house price growth and the significant increase in interest rates from the record lows during COVID, mortgages have risen considerably more than rent prices," she said.
"The average loan in Perth is now about $720,000 and the monthly mortgage repayment based on the average loan has increased from $1,902 in the March 2022 quarter, before rates started rising in May 2022, to $4,428, which is 132.8 per cent higher.
"By comparison, median rents have increased 62.2 per cent over the same timeframe.
"While the current market may offer better conditions for buyers than we've seen in years, assuming a tenant will be able to buy a home if an investor sells the property they are renting is unrealistic."
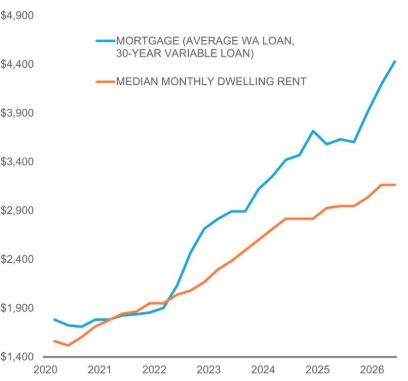
Source: REIWA. Based on the average WA mortgage over 30 years at the variable large institution owner-occupier interest rate compared with the Perth median dwelling rent price.
Ms Brown said the data emphasised the need for policy settings that supported rental supply.
"There has been a lot of commentary that investors selling in the wake of the reforms to WA's tenancy legislation announced in May and the taxation changes announced in the Federal Budget was a positive for tenants rather than a negative," she said.
"However, whenever REIWA expresses concern about rental supply and investors leaving the market, a common response is that it gives a tenant an opportunity to buy.
"The data shows buying a home isn't going to be financially feasible for many people if an investor sells the home they are renting. In addition, they may also not want to buy.
"People rent for many reasons, they may be building and waiting for their new home to be completed. They may be working in the country for a period of time and don't want to buy. They may be renting because they want to be in a certain area but can't afford to buy a home there.
"We also need to acknowledge that many tenants are simply not in a position to buy a home at a certain point in their lives. They may not have saved a deposit. They may not be able to service a mortgage at that time.
"And, unfortunately, some tenants will never be able to buy a home. There are older Australians who reach retirement while still renting. They're living on a pension with no capacity to borrow and no deposit behind them. Single mature women often find themselves renting after a separation or the death of a partner, having been left with a settlement or superannuation balance that is not going to help them buy a house. There are people on a disability support pension or a carer's payment.
"None of these tenants will be able to buy the home they are living in if it is sold. For them, losing a rental is a crisis, not an inconvenience. They will join the queue for whatever is available, competing against applicants with higher incomes and stronger rental histories.
"While home ownership remains unattainable for many people, we need to ensure we have a healthy rental market. And until governments or other organisations can provide alternative options in large enough numbers, that means we need investors."
For tenants aspiring to house ownership within the same suburb, the most economical prospects were Bullsbrook, Stratton and Midland. Mortgages payments were no more than 15 per cent greater than rent payments in these suburbs.
The unit market offered better opportunities.
"There are eight suburbs in Perth where the median monthly mortgage is less than the median monthly rent," Ms Brown said.
"Glendalough has the greatest different, with its monthly mortgage of $2,505 being $442 cheaper than monthly rent costs of $2,947. That's a 17.7 per cent difference.
"West Leederville and Belmont are the next best options, with differences of 4.6 and 2.4 per cent respectively.
"The data also highlights why some people choose to rent in a certain suburb instead of buying there.
"A common reason is they want to be in a particular school catchment area. Shenton Park is one example as Shenton College is a very popular school. The monthly mortgage payment on a median-priced house in Shenton Park is $12,424, while the median house rent is $4,450. That's a difference of $7,874 or 63.4 per cent.
"Rossmoyne is another example. The median monthly house rent payment is $4,450 while the mortgage payment based on the median house sale price is $10,579, a 57.0 per cent difference."
Top 10 most economical Perth suburbs to rent v buy - houses
| Suburb | Annual median house sale price* (August 2026) | Median weekly house rent 3-months to August 2026 | Monthly house rent | Monthly mortgage repayment** | Rent vs buy | Rent vs buy % |
| Bullsbrook | $800,000 | $790 | $3,423 | $3,936 | -$531 | -13.0% |
Stratton |
$755,000 | $730 | $3,163 | $3,715 | -$552 | -14.8% |
| Midland | $710,000 | $685 | $2,968 | $3,494 | -$525 | -15.0% |
| Langford | $780,000 | $750 | $3,250 | $3,838 | -$588 | -15.3% |
| Huntingdale | $822,500 | $780 | $3,380 | $4,047 | -$667 | -16.5% |
| Beckenham | $850,000 | $800 | $3,467 | $4,182 | -$716 | -17.1% |
| Bentley | $850,000 | $800 | $3,467 | $4,182 | -$716 | -17.1% |
| Brabham | $874,250 | $820 | $3,553 | $4,302 | -$748 | -17.4% |
| Midvale | $800,000 | $750 | $3,250 | $3,936 | -$686 | -17.4% |
| Cannington | $802,500 | $750 | $3,250 | $3,949 | -$699 | -17.7% |
Top 10 most economical Perth suburbs to rent v buy - units
| Suburb | Annual median unit sale price* (August 2026) | Median weekly unit rent 3-months to August 2026 | Monthly unit rent | Monthly mortgage repayment** | Rent vs buy | Rent vs buy % |
| Glendalough | $509,000 | $680 | $2,947 | $2,505 | $442 | 17.7% |
| West Leederville | $665,000 | $790 | $3,423 | $3,272 | $151 | 4.6% |
| Belmont | $596,000 | $700 | $3,033 | $2,933 | $101 | 3.4% |
| Cannington | $619,000 | $720 | $2,120 | $3,046 | $74 | 2.4% |
| Perth | $648,000 | $750 | $3,250 | $3,189 | $61 | 1.9% |
| Cloverdale | $605,000 | $700 | $3,033 | $2,977 | $56 | 1.9% |
| Beckenham | $565,000 | $650 | $2,817 | $2,780 | $37 | 1.3% |
| Northbridge | $660,000 | $750 | $3,250 | $3,248 | $2 | 0.1% |
| East Perth | $690,000 | $780 | $3,380 | $3,395 | -$15 | -0.4% |
| Wembley | $557,475 | $630 | $2,730 | $2,743 | $-13 | -0.5% |
Source: REIWA. Filtered for suburbs with 28 or more house or unit sales in the year to August 2026 and 7 or more house or unit leases in the three months to the end of August 2026.
Units include villas, townhouses, apartments, flats and home units.
* REIWA publishes an annual median sale price based on pending and settled sales of properties on less than 1 hectare.
** Based on the median sale price, with a 20 per cent deposit and assuming a 30-year mortgage, on a 6.24 per cent variable rate, which is the July owner-occupier variable lending rate for large institutions.


